

Automotive Grade Smart Cockpit SoC Market Report Covers Key Segments, Regional Developments, and Leading Competitors
Automotive Grade Smart Cockpit SoC Market Growth

Automotive Grade Smart Cockpit SoC Market Analysis

Automotive Grade Smart Cockpit SoC Market Overview
The Business Research Company’s Automotive Grade Smart Cockpit SoC Global Market Report 2026 – Market Size, Trends, And Forecast 2026-2035
LONDON, GREATER LONDON, UNITED KINGDOM, October 27, 2026 /EINPresswire.com/ -- The automotive electronics sector is rapidly evolving, with smart cockpit system-on-chip (SoC) technologies playing a crucial role in transforming in-vehicle experiences. As vehicles become more connected, digitalized, and software-driven, the Automotive Grade Smart Cockpit SoC market is set to witness significant growth and reshape automotive design and functionality over the next decade. Below is an in-depth exploration of this market’s size, regional outlook, key drivers, leading players, and emerging trends.
Market Size and Its Position Within the Automotive Industry
The Automotive Grade Smart Cockpit SoC market is projected to exceed $6 billion by 2030. In comparison, its broader parent market—the Motor Vehicle Engine, Power Train & Parts sector—is expected to reach about $1,213 billion by the same year, with smart cockpit SoCs accounting for roughly 1% of that total. When viewed within the expansive Transport industry, which is forecasted to be valued at $9,400 billion by 2030, the smart cockpit SoC segment represents close to 0.1% of the entire market value. This niche, while relatively small, is gaining prominence as automotive electronics become more complex and integrated.
Request A Free Sample Of The Automotive Grade Smart Cockpit SoC Market Report
https://thebusinessresearchcompany.com/sample_request?id=21399&type=smp&name=Automotive%20Grade%20Smart%20Cockpit%20System-On-Chip%20%28SoC%29%20Market%20Report%202026&utm_source=EINPresswire&utm_medium=Paid&utm_campaign=Oct_PR
Asia-Pacific Set to Lead the Automotive Grade Smart Cockpit SoC Market Growth
By 2030, the Asia-Pacific region will be the largest market for automotive grade smart cockpit SoCs, holding a value of $3.1 billion. This is poised to grow from $1.7 billion in 2025 at a compound annual growth rate (CAGR) of 13%. The rapid expansion is driven by several factors, including the swift adoption of electric and connected vehicles in key countries, the growing implementation of advanced infotainment and digital instrument cluster systems, consumer demand for personalized and enhanced cockpit interfaces, strengthening semiconductor design and manufacturing capabilities, and heavy investments by automotive original equipment manufacturers (OEMs) in next-gen vehicle electronics and software-defined architectures, particularly across China, Japan, South Korea, and India.
China Emerging as the Dominant National Market for Smart Cockpit SoCs
China is forecast to be the largest country-specific market within the automotive grade smart cockpit SoC space by 2030, valued at $1.8 billion. This represents a growth from $0.9 billion in 2025, with a steady CAGR of 13%. Factors propelling this growth include the rapid expansion of domestic electric vehicle production, the maturation of smart mobility ecosystems, integration of high-performance cockpit computing hardware in both mass-market and premium vehicles, strong government initiatives supporting semiconductor localization and supply chain independence, increased use of voice assistants and multi-display cockpit systems, and ongoing investments by Chinese automakers and tech firms focusing on vehicle intelligence and in-car operating systems.
Access The Detailed Automotive Grade Smart Cockpit SoC Market Report Here
https://thebusinessresearchcompany.com/report/automotive-grade-smart-cockpit-system-on-chip-soc-global-market-report?utm_source=EINPresswire&utm_medium=Paid&utm_campaign=Oct_PR
Infoainment System-on-Chip to Dominate Product Segments in 2030
Within the automotive grade smart cockpit SoC market, product segmentation includes infotainment system-on-chip (SoC) and instrument cluster system-on-chip (SoC). The infotainment SoC segment will be the largest, accounting for 60% of the market—or $4 billion—by 2030. This dominance is fueled by the rising incorporation of high-resolution multi-display setups, immersive multimedia systems, demand for sophisticated human-machine interactions with real-time responsiveness, cloud-connected entertainment ecosystems inside vehicles, software-defined vehicle platforms allowing continuous feature enhancements, and collaborations between automotive manufacturers and semiconductor companies aimed at boosting processing power and system efficiency.
Diverse Technology Segments Powering the Smart Cockpit SoC Market
The automotive grade smart cockpit SoC market consists of multiple technology segments including three-dimensional (3D) graphics, artificial intelligence (AI), voice recognition, connectivity solutions, and other related technologies. These technological innovations collectively enable smarter, safer, and more interactive vehicle cockpits that cater to future mobility trends.
Passenger Cars and Commercial Vehicles as Major Application Areas
This market is categorized based on applications into passenger cars and commercial vehicles. Both sectors are increasingly relying on smart cockpit SoC solutions to enhance driver assistance, infotainment capabilities, and safety features, reflecting a widespread automotive shift toward digitalized and connected vehicle systems.
Market Expected to Grow at a Solid Pace Through 2030
The Automotive Grade Smart Cockpit SoC market is projected to expand at a compound annual growth rate of 12% leading up to 2030. This strong growth outlook stems from multiple converging industry trends and technological advancements.
Rising Demand for Connected and Digitally Enhanced In-Vehicle Experiences
A primary growth driver for this market is the escalating consumer expectation for vehicles to offer connected, digital experiences akin to smartphones. Features such as AI-based voice assistants, navigation aids, multimedia streaming, and seamless connectivity are becoming standard demand elements. Automotive OEMs are responding by integrating larger digital dashboards, infotainment displays, and multi-screen cockpit systems that require powerful SoCs capable of handling simultaneous data processing for graphics, connectivity, and user interactions. This increasing demand is expected to contribute an approximate 3.0% annual growth to the market.
Increasing Use of AI and Advanced Driver Assistance Systems in Cockpit Features
Another significant factor fueling market expansion is the adoption of AI-driven cockpit functionalities and advanced driver assistance systems. These solutions combine infotainment, driver monitoring, navigation, and safety features into centralized computing platforms. Smart cockpit SoCs enable real-time processing for facial recognition, voice commands, driver behavior analytics, and augmented reality displays. The demand for low-latency, high-reliability semiconductor platforms is growing as automakers aim to streamline hardware and enhance vehicle intelligence. This factor is projected to add around 2.7% annual growth to the market.
Widespread Adoption of Electric and Software-Defined Vehicles Boosting Market Growth
The shift toward electric vehicles (EVs) and software-defined vehicle architectures is another key driver for the smart cockpit SoC market. EV manufacturers emphasize digital cockpit innovation with features such as large touchscreen displays, intelligent connectivity, over-the-air software updates, and immersive infotainment environments that depend on robust SoCs for smooth performance. Software-defined vehicles consolidate multiple electronic controls into high-performance platforms, further increasing demand. This trend is expected to contribute roughly 2.5% annual market growth.
Promising Growth Opportunities Within Key Product Segments
The infotainment and instrument cluster system-on-chip markets represent the most lucrative opportunities, projected to collectively add over $3 billion in value by 2030. Growth is propelled by the move toward centralized vehicle computing that replaces distributed electronic control units (ECUs), increasing deployment of AI-based personalized driver interfaces, real-time sensor fusion, high-speed data processing within digital cockpits, expansion of automotive-grade semiconductor manufacturing, and wider integration of over-the-air update capabilities for continuous system improvements. This reflects the broader transition to software-defined vehicles offering enhanced cabin intelligence and immersive driving experiences.
Market Composition Featuring Global Semiconductor Leaders and Specialized Providers
The automotive grade smart cockpit SoC market is characterized by a mix of global semiconductor giants and niche automotive chip specialists. These companies focus on developing high-performance computing architectures, AI-powered infotainment processing, multi-display integration, and advanced connectivity solutions to meet growing demands for vehicle digitalization. Emphasis on functional safety, power efficiency, real-time processing, and compatibility with driver assistance and in-vehicle operating systems remains crucial. Understanding this competitive landscape is vital for stakeholders pursuing innovation, growth, and strategic collaborations in this fast-evolving sector.
Qualcomm Technologies Inc. Leading the Market in 2025
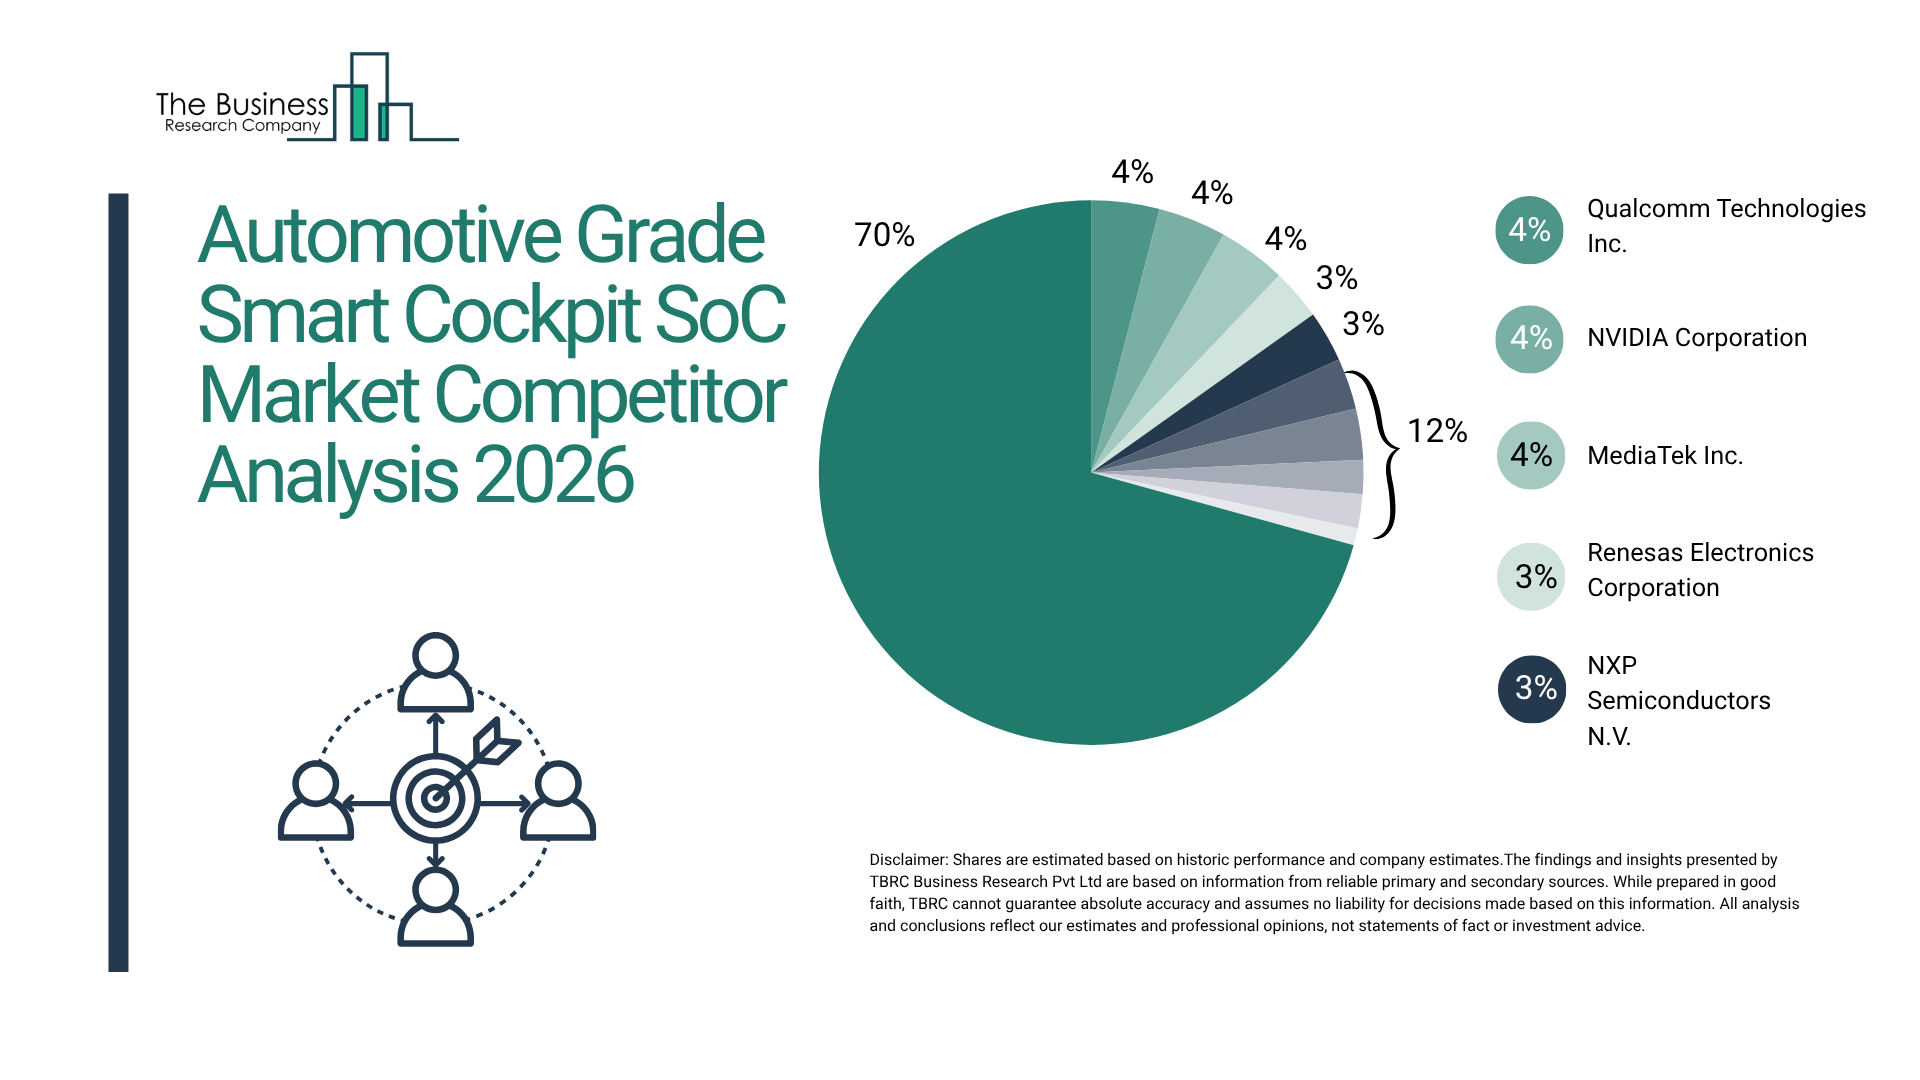
Research indicates Qualcomm Technologies Inc. led global smart cockpit SoC sales in 2025 with a 4% market share. Their automotive solutions division offers a wide spectrum of high-performance system-on-chip platforms, AI-enabled cockpit processors, integrated infotainment and connectivity technologies, and advanced computing architectures that support next-generation connected and autonomous vehicle platforms.
Key Players Shaping the Automotive Grade Smart Cockpit SoC Industry
Major companies active in this market include Qualcomm Technologies Inc., NVIDIA Corporation, MediaTek Inc., Renesas Electronics Corporation, NXP Semiconductors N.V., Samsung Electronics Co. Ltd., Texas Instruments Incorporated, STMicroelectronics N.V., Infineon Technologies AG, Horizon Robotics, Nanjing SemiDrive Technology, SiEngine Technology Co. Ltd., Telechips Inc., UNISOC Communications, ECARX Group, Rockchip Electronics Co. Ltd., Black Sesame Technologies, Amlogic Inc., Allwinner Technology Co. Ltd., Ambarella Inc., and VeriSilicon Holdings Co. Ltd.
Market Structure is Moderately Fragmented with Notable Concentration
The automotive grade smart cockpit SoC market is moderately fragmented; the top 10 companies held 30% of the market revenue in 2025. Entry barriers remain significant due to strict automotive safety regulations, complex semiconductor design requirements, high research and development costs, extended product validation times, and the necessity for automotive-grade quality certifications. Major players like Qualcomm, NVIDIA, MediaTek, Renesas, NXP, Samsung, Texas Instruments, STMicroelectronics, Infineon, and Horizon Robotics maintain strong footholds through diversified portfolios, OEM partnerships, global supply chains, and continued innovation in smart cockpit technologies. As demand for advanced infotainment, AI-driven cockpit systems, multi-display setups, and connected mobility rises, strategic collaborations and product advances will shape future competitiveness.
Leading Companies in the Automotive Grade Smart Cockpit SoC Market
• Qualcomm Technologies Inc. (4%)
• NVIDIA Corporation (4%)
• MediaTek Inc. (4%)
• Renesas Electronics Corporation (3%)
• NXP Semiconductors N.V. (3%)
• Samsung Electronics Co. Ltd. (3%)
• Texas Instruments Incorporated (3%)
• STMicroelectronics N.V. (2%)
• Infineon Technologies AG (2%)
• Horizon Robotics (1%)
Key Suppliers of Raw Materials Supporting the Market
Prominent suppliers of essential raw materials include TSMC (Taiwan Semiconductor Manufacturing Company Limited), Samsung Electronics Co. Ltd., Intel Corporation, NVIDIA Corporation, Qualcomm Incorporated, Advanced Micro Devices Inc., Broadcom Inc., NXP Semiconductors N.V., Infineon Technologies AG, STMicroelectronics N.V., Renesas Electronics Corporation, MediaTek Inc., Texas Instruments Incorporated, ON Semiconductor Corporation, Microchip Technology Incorporated, Analog Devices Inc., Marvell Technology Inc., Cypress Semiconductor Corporation, Rohm Co. Ltd., Sony Semiconductor Solutions Corporation, Toshiba Electronic Devices and Storage Corporation, SK Hynix Inc., Micron Technology Inc., GlobalFoundries Inc., and United Microelectronics Corporation.
Major Wholesalers and Distributors in the Automotive Grade Smart Cockpit SoC Market
Leading wholesalers and distributors include Arrow Electronics Inc., Avnet Inc., Ingram Micro Inc., Tech Data Corporation, Synnex Corporation, Future Electronics Inc., Digi-Key Electronics, Mouser Electronics Inc., RS Components Limited, TTI Inc., Allied Electronics and Automation, Macnica Inc., EET Group A/S, ScanSource Inc., Westcon Group, Exclusive Networks SA, ALSO Holding AG, Esprinet S.p.A., Redington Limited, Logicom Public Limited, ASBIS Enterprises PLC, Bechtle AG, Cancom SE, CDW Corporation, and Insight Enterprises Inc.
Primary End Users Driving Demand for Smart Cockpit SoCs
The main end users benefiting from automotive grade smart cockpit SoC technologies include Tesla Inc., Toyota Motor Corporation, BMW Group, Mercedes-Benz Group AG, Volkswagen AG, General Motors Company, Ford Motor Company, Hyundai Motor Company, Kia Corporation, Honda Motor Co. Ltd., Nissan Motor Company Limited, Stellantis N.V., BYD Company Limited, Geely Automobile Holdings Limited, SAIC Motor Corporation Limited, Renault Group, Subaru Corporation, Mazda Motor Corporation, Volvo Car Corporation, Jaguar Land Rover Automotive PLC, Tata Motors Limited, Rivian Automotive Inc., Lucid Group Inc., NIO Inc., and XPeng Inc.
Competitive Market Trends Shaping the Industry Landscape
AI-driven system-on-chip platforms are revolutionizing the automotive grade smart cockpit sector by enabling real-time data processing, improved infotainment, and cutting-edge in-car connectivity. For example, in March 2024, MediaTek introduced the Dimensity Auto cockpit chipsets designed for next-generation intelligent vehicles, featuring AI and high-performance computing capabilities. These chipsets combine Armv9-A CPUs, NVIDIA RTX graphics, and Deep Learning Accelerators to support natural language processing, conversational AI, and immersive multi-display infotainment.
Strategies Companies Employ to Maintain Market Leadership
To stay competitive, firms are advancing smart cockpit SoC architectures to enhance real-time processing and user experience, utilizing high-performance AI chipsets that support infotainment and connectivity, expanding integrated SoC platforms to boost cockpit efficiency and design flexibility, and incorporating AI and sensor fusion technologies to improve personalization and safety monitoring features inside vehicles.
What’s included in our 2026 market reports:
• Market attractiveness scoring and analysis
• Total addressable market (TAM) analysis
• Company scoring matrix graphics and tables
• Excel-based forecasting dashboards
• Market hotspots infographics
• Key technologies and future trend analysis
• Updated graphics and tables
Learn More About The Business Research Company
The Business Research Company (www.thebusinessresearchcompany.com) is a leading market intelligence firm renowned for its expertise in company, market, and consumer research. We have published over 30,000+ reports across 27 industries and 60+ geographies. Our research is powered by 1,500,000 datasets, extensive secondary research, and exclusive insights from interviews with industry leaders.
We provide continuous and custom research services, offering a range of specialized packages tailored to your needs, including Market Entry Research Package, Competitor Tracking Package, Supplier & Distributor Package and much more.
Disclaimer: Please note that the findings, conclusions and recommendations that TBRC Business Research Pvt Ltd delivers are based on information gathered in good faith from both primary and secondary sources, whose accuracy we are not always in a position to guarantee. As such TBRC Business Research Pvt Ltd can accept no liability whatever for actions taken based on any information that may subsequently prove to be incorrect. Analysis and findings included in TBRC reports and presentations are our estimates, opinions and are not intended as statements of fact or investment guidance.
Contact Us:
The Business Research Company
Americas +1 310-496-7795
Europe +44 7882 955267
Asia & Others +44 7882 955267 & +91 8897263534
Email: marketing@tbrc.info
Follow Us On:
LinkedIn: https://in.linkedin.com/company/the-business-research-company
Oliver Guirdham
The Business Research Company
+44 7882 955267
Visit us on social media:
LinkedIn
Facebook
X
Legal Disclaimer:
EIN Presswire provides this news content "as is" without warranty of any kind. We do not accept any responsibility or liability for the accuracy, content, images, videos, licenses, completeness, legality, or reliability of the information contained in this article. If you have any complaints or copyright issues related to this article, kindly contact the author above.
